Mohammad H. Seyedsalehi — economist
I am a PhD candidate in Economics at the University of Toronto, specializing in empirical industrial organization, environmental economics, and econometrics. I study pricing and competition in vertically linked markets, carbon policy design, dynamic firm behavior, and climate finance. My parallel econometric research focuses on empirical Bayes methods and the structural estimation of dynamic models.
I am on the 2026–2027 economics job market.
01 / Working papers
Job Market Paper
Decarbonization Policy Along the Fuel Supply Chain: A Structural Analysis of Brazil’s RenovaBio
Abstract: Decarbonization Policy Along the Fuel Supply Chain: A Structural Analysis of Brazil’s RenovaBio
Incentivizing biofuel production is a widely used strategy for reducing transport emissions, but its effectiveness depends on whether additional biofuel replaces fossil fuels or expands total fuel consumption. The outcome depends in turn on the way production incentives transmit through wholesale markets and fuel distributors set consumer prices. To quantify these channels, I develop and estimate a structural equilibrium model linking ethanol production, the wholesale ethanol market, retail competition between fuel distributors, and a dynamic market for tradable decarbonization credits. I apply the model to Brazil’s RenovaBio program, under which biofuel producers earn credits that fossil fuel distributors are required to purchase then retire, thus financing the transition to cleaner energy within the industry. The model incorporates heterogeneous ethanol supply responses associated with sugarcane and corn production, consumer choice between ethanol and gasoline, and credit banking for future compliance. The estimates imply that most of the production incentive reaches consumers through lower ethanol prices. Relative to a counterfactual without RenovaBio, the program increases ethanol production but leaves gasoline consumption almost unchanged, raising total fuel use by approximately 0.7% over 2020–2024. Despite government-reported emissions savings equivalent to roughly 15% of Brazil’s transport emissions, I find that the program instead increases estimated emissions by 0.22%. Further, policy simulations indicate that the same ethanol production along with 1.20% lower emissions and higher welfare could be achieved using an ethanol blending requirement around one percentage point higher. The analysis underscores why evaluating biofuel policies requires production incentives, credit-market equilibrium, and downstream competition and demand to be jointly accounted for.
Empirical Bayes with Side Information: Incorporating Geographic Relevance into Neighborhood Impact Estimation
Second revise and resubmit, Journal of Applied Econometrics
Abstract: Empirical Bayes with Side Information: Incorporating Geographic Relevance into Neighborhood Impact Estimation
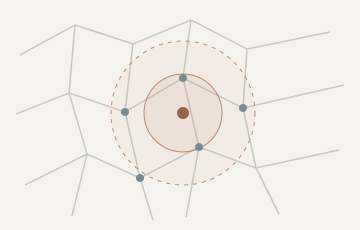
This paper introduces a novel methodology for estimating neighborhood impacts on intergenerational mobility. The approach employs a nonparametric empirical Bayes framework that addresses geographic heterogeneity in the underlying data-generating process. First, I propose a theoretical framework to address the long-standing yet unresolved question of how to make better use of highly relevant samples—in this context, data from geographically closer regions—when designing a shrinkage estimator for a target area. I demonstrate, both theoretically and empirically, how neglecting this factor can lead to systematically distorted estimates. Second, using publicly available data, I demonstrate that the relevance-based empirical Bayes method reduces Mean Squared Error (MSE) by 26% to 34% relative to benchmark estimates.
02 / Publications
The Effects of Order Flow Imbalance on Stock Prices in Tehran Stock Exchange
With Mahdi Barakchian
Financial Management Perspective, 2022
Abstract: The Effects of Order Flow Imbalance on Stock Prices in Tehran Stock Exchange
We investigate the effects of order-book events on the prices of the 30 largest stocks on the Tehran Stock Exchange during 2020. We measure the sensitivity of prices to changes in supply and demand volumes and identify the factors affecting this sensitivity. Following the approach of Cont et al. (2014), we conduct approximately 30,000 OLS regressions and show that, in a low-depth market, mid-price returns are significantly explained by order flow imbalance, which captures the net change in demand—that is, the difference between event volumes on the two sides of the order book. We also show that incorporating order flow imbalance from the first three levels of the order book increases the model’s explanatory power for changes in stock mid-prices, indicating that deeper levels of the order book also significantly affect price changes. Moreover, the results confirm that market depth reduces the price impact of order-book events. Our findings are robust across months and stocks.
03 / Work in progress
Euler Equations for Dynamic Games
With Victor Aguirregabiria
Abstract: Euler Equations for Dynamic Games
Decisions about market entry, capital investment, and innovation are inherently forward-looking, requiring firms to anticipate both future market conditions and their competitors' reactions. This project develops a computationally tractable framework for recovering the dynamic incentives underlying these decisions in oligopoly markets. Rather than relying on repeated solutions of the dynamic game, we use estimated firm strategies to construct optimality restrictions that connect marginal payoffs across three periods. Exploiting finite-dependence properties, we derive Euler equations that remove continuation-value derivatives while preserving the effects of strategic interactions. The approach extends conventional Euler-equation methods to dynamic games and provides a practical foundation for structural estimation in models of entry and exit, investment, and innovation.
Who Benefits from Green Subsidies? Labor Standards and the Distribution of Gains
With Zahra Sedaghat
Abstract: Who Benefits from Green Subsidies? Labor Standards and the Distribution of Gains
How are the gains from green investment subsidies distributed between firms and workers? This project examines whether labor conditions attached to these subsidies increase workers’ share of the benefits, using Canada’s Clean Technology Investment Tax Credit. The policy offers a larger credit to firms meeting prevailing-wage and apprenticeship requirements, linking investment support to employment practices. The analysis links firms’ investment and contractor choices to worker earnings. Firms can qualify for additional support without raising existing workers’ pay if they already meet the standards or hire contractors that do. Higher wages at subsidized projects therefore need not reflect gains caused by the policy. Comparing subsidies with and without labor conditions at the same fiscal cost would assess whether these requirements increase worker earnings and training opportunities, and how they affect investment and hiring.
One Carbon Market or Many? Optimal Integration of Sectoral Carbon Markets
Abstract: One Carbon Market or Many? Optimal Integration of Sectoral Carbon Markets
This paper asks whether carbon credit markets that jointly penalize dirty activity and reward clean activity should be organized separately by sector or integrated into a common market. Integration can establish a common carbon price, equalizing marginal abatement costs across sectors and shifting emissions reductions toward lower-cost opportunities, while also allowing payments from dirty activity in one sector to finance clean investment in another. Separation, however, preserves sector-specific certificate prices, allowing clean incentives to respond independently to differences in innovation and adoption frictions. I study a market design in which clean activities generate tradable certificates and dirty activities create demand for the same asset, with sector-specific crediting and obligation rates determining the effective clean subsidy and carbon penalty. I characterize when a unified market can achieve the efficient combination of a common carbon price and differentiated clean-technology support, when separate sectoral markets perform better, and how this tradeoff depends on abatement costs and clean-technology spillovers across sectors.
04 / Teaching
I have served as a teaching assistant for more than 2,000 assigned hours during my PhD at the University of Toronto, across undergraduate and graduate courses, with a focus on machine learning, data science, and finance. Before my PhD, I spent seven years teaching mathematics to International Mathematical Olympiad students.
Teaching experience
- Machine Learning Applications in Economics and Finance (5 semesters)
- Financial Economics, Banking, and Corporate Finance (3 semesters)
- Financial Risk Management (3 semesters)
- Microeconomics and macroeconomics
- Environmental and climate economics
- Data analysis and programming
- International trade and economics for public policy